
AI Summary
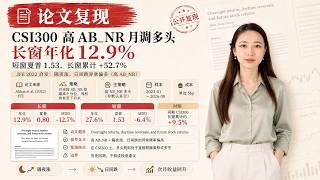
This video presents a backtest of the ABNR (overnight reversal) signal on the CSI 300 index, adapted from a US equity study. The main long-only strategy—buying the top decile of ABNR each month—delivered 12.9% annualized with a downside deviation of 0.80, beating the index's 2.5%. However, the long-short version failed, and the study emphasizes survivorship bias and short sample windows as key limitations.
Chapters
The main tradable strategy is a long-only CSI 300 high-ABNR portfolio: monthly buy top decile, equal-weight, hold to next month-end. Long-window cumulative return 52.7%, annualized 12.9%, downside deviation 0.80, vs index annualized 2.5%.
Sample covers Jan 2023–Aug 2026 (42 months) using current CSI 300 constituents, introducing survivorship bias. Short-window strength cannot be extrapolated as stable returns.
ABNR is constructed from daily open/close prices: separate intraday and overnight returns, flag days where overnight is up and intraday is down, compute monthly frequency, then standardize over past 12 months.
Original study used US stock database (May 1993–Dec 2017). This study uses domestic open-source data for CSI 300 current constituents, daily data from Jan 4, 2022 to Sep 3, 2026.
Long-short rule nearly fails in CSI 300 long window. The tradable interpretation is revised to high-ABNR long-only. No modeling of price limits, suspensions, or impact costs.
Long-only clearly outperforms index; long-short weakens with deeper drawdowns. Short window (16 months) shows positive returns but too short for standalone conclusions.
Long window: cumulative 52.7%, annualized 12.9%, downside 0.80, max drawdown -12.7%. Index: cumulative 9.5%, annualized 2.5%, max drawdown -21.0%. Long-short cumulative -8.1%.
Short window (16 months): long-only cumulative 38.4%, annualized 27.6%, Sharpe 1.53. Strong but only for recent observation, not a substitute for long-window stability.
Portfolio ~30 stocks equal-weight, month-end rebalance. Costs ~5bp per side deducted; no coverage of price limits, suspensions, impact, or execution deviation—real returns may be lower.
Only high-ABNR long works; short leg fails. Signal is asymmetric—use ABNR as a stock-selection and portfolio construction signal, not as a guaranteed mechanism.
Use long window to decide whether to track the strategy; use short window to observe return decay. Don't add leverage based on 16-month 27.6% annualized.
Don't naively short the bottom decile in CSI 300; long-short cumulative -8.1% in long window, financing costs may worsen. Don't extrapolate current-constituent results to all A-shares.
ABNR can form a monthly equal-weight executable stock-selection process. Long-window cumulative 52.7%, annualized 12.9%, downside 0.80, better than index's 2.5%—a candidate for portfolio enhancement.
Don't copy US long-short results. Returns are strong but only 16 months; validate further. Before going live, incorporate survivorship bias, price limits, turnover impact, financing costs, and capacity.
The ABNR long-only strategy on CSI 300 shows strong risk-adjusted returns (12.9% annualized vs 2.5% index), but the long-short version fails and the sample is short with survivorship bias. Use it as a candidate for portfolio enhancement, not a guaranteed edge.
Mentioned in this Video
Tutorial Checklist
💡 Key Takeaways
Long-only ABNR outperforms index
Shows a concrete, tradable edge over the benchmark with a 12.9% vs 2.5% annualized return.
00:43Long-short fails in CSI 300
Highlights that US long-short results don't transplant directly to A-shares.
02:20ABNR construction method
Provides a clear, reproducible signal based on open/close prices.
01:08Use ABNR as selection signal, not mechanism
Cautions against over-interpreting the signal's economic story.
04:29Cost-adjusted performance
Shows the strategy remains attractive after ~5bp per side costs.
05:19Full Transcript
[00:00] 本期附现一篇,隔夜日内反转研究,打开收盘价够高的ADNR信号落在沪深300上,长窗扣分年化收益12.9%,下谱0.80,本回测改成值多多,每月末买入ADNR最高10分位,并等权,持有至下月末,不搬每股市多空,样本仅覆盖2023年1月至2026年8月,且采用当前沪深300成分,存在存活偏差,短窗强势不能直接外推,为稳定收益。
[00:30] 5月把主结论先掏开 本回收的可交易主策略是 沪深300高ABN2多头 长窗扣费后累计52.7% 年化12.9%
[00:43] 下谱0.80 同期指数年化仅2.5% 每月末买入ABN2最高10分位 并等权持有至下月末 只做多不做空 长窗多空对照反而为负
[00:56] 量本只有2023年1月至2026年8月 并采用当前护身三改成分 因此存活偏差和短窗强势都不能直接外推为稳定收益 月度调仓
[01:08] 从每日前付全开盘价和收盘价开始拆除日内收益与隔夜收益 把隔夜上涨前日内下跌的样本记为复日间反转日 每月先算齐占比NR
[01:21] 但用过去12个月精致标准化得到ABNR需积累12个月历史月末按ABNR从低到高排成10组,买入最高10分位全部成分等权,持有至下月末,再换仓主策略多头,每次约扣单边5个基点LS对照,按两小腿约10BP扣减,不做空,最低10分位全部成分等权,持有至下月末,再换仓主策略多头,每次约扣单边5个基点LS对照,
[01:52] 地案两条腿约10BP扣减不做空最低十分位 原文基于美股股票数据库日开盘和收盘数据 样本从1993年5月到2017年12月
[02:05] 主组合强调本权高减低多空 本研究改用国内开源行情源的前赋 全入行情覆盖沪深三百当前成分 日行情从2022年1月4日到2026年9月3日
[02:20] 祖国窗口从2023年1月到2026年8月 因为ADNR需积累12个月历史信号 而言文多空规则 在沪深300长窗巨额接近失效
[02:32] 于是把可交易解读修正为高ADNR多头 为做实质加权 也尚未建模涨跌停 停牌跳过和冲击成本 因此存在存活偏差 自路地方长窗里
[02:44] Long Night明显高于同期指数 而LS Night整体走弱且回撤更深控头腿在护身三板上脱泪明显转窗里allnetlf net虽都转正但转窗只有16个月不能单独作为订餐依据
[02:58] 途中回撤也提醒高ABNR多头并非无回撤策略 长窗最大回撤仍达到-12.7% 因此不能把原研究的美股多空差 直接清理为A股交易预期
[03:10] 自扣费主结果呈现的很清楚 短量本42个月里高ABNR 多头的累计为52.7% 年化12.9% 下谱0.80
[03:22] 最大回撤-12.7% 同期指数累计只有9.5% 年化2.5% 最大回撤却达-21.0% 长窗多空对照累计-8.1%
[03:36] 下谱接近0 不适合作为默认识盘规则 短量本16个月里多头累计 38.4% 年化27.6% 夏普1.53% 虽强力长仓
[03:48] 但只能作为近况观察 不能替代长仓稳定性检验 不强势力机制 需要分开看 组合约30只股票等权 持有并用月末换仓 表内All in it
[04:00] 已按约单边5GP扣除减化成本 单位覆盖涨跌停 停跑开膨速进冲击 和实际成交偏离 实盘收益可能更低 安窗只有高ADNR多头有效
[04:12] 多空腿失效 信号可用部分主要集中在多头端同时ADPR多空并未稳定若与ABNR原有方向不对称解释尚未稳定验证因此本研究只把ABNR当作选股和组合构建信号
[04:29] 不把机制故事视作以正式的收益保证 若是幽默计算 ABNR并持有最高10分位等全头头 用长窗判断是否值得继续跟踪 用短窗观察收益是否衰减
[04:42] 但不能因缘16个月年化27.6% 下谷1.53 就单独加仓 做的是核对 成分调整 平台 涨跌停和月末成交10点 确认约5GP成本
[04:54] 假设是否现实 别做的是在沪深300上默认裸作空 最低时分位 拼多空 长窗累计 负8.1% 融券与采差成本可能更差 也不能把当前成分回撤外退到全A股
[05:07] 混用美股 多空差 当作本策略预期收益 其中可带走的结论是 用开盘价与收盘价度造ABNR 可以形成月平等权 可执行的粉股流程
[05:19] 长长扣费后累积52.7% 年化12.9% 下谱0.80% 优于同期沪深300的年化2.5% 资质跟踪的组合增强候选
[05:31] 不支持照搬美股市高低股多空转创 收益虽强但只有16个月 更适合继续外汇验证 落地前需把当前成分所获偏差 平台涨跌停 换手冲击
[05:43] 融资融券费用和实际容量 纳入交易检查资格